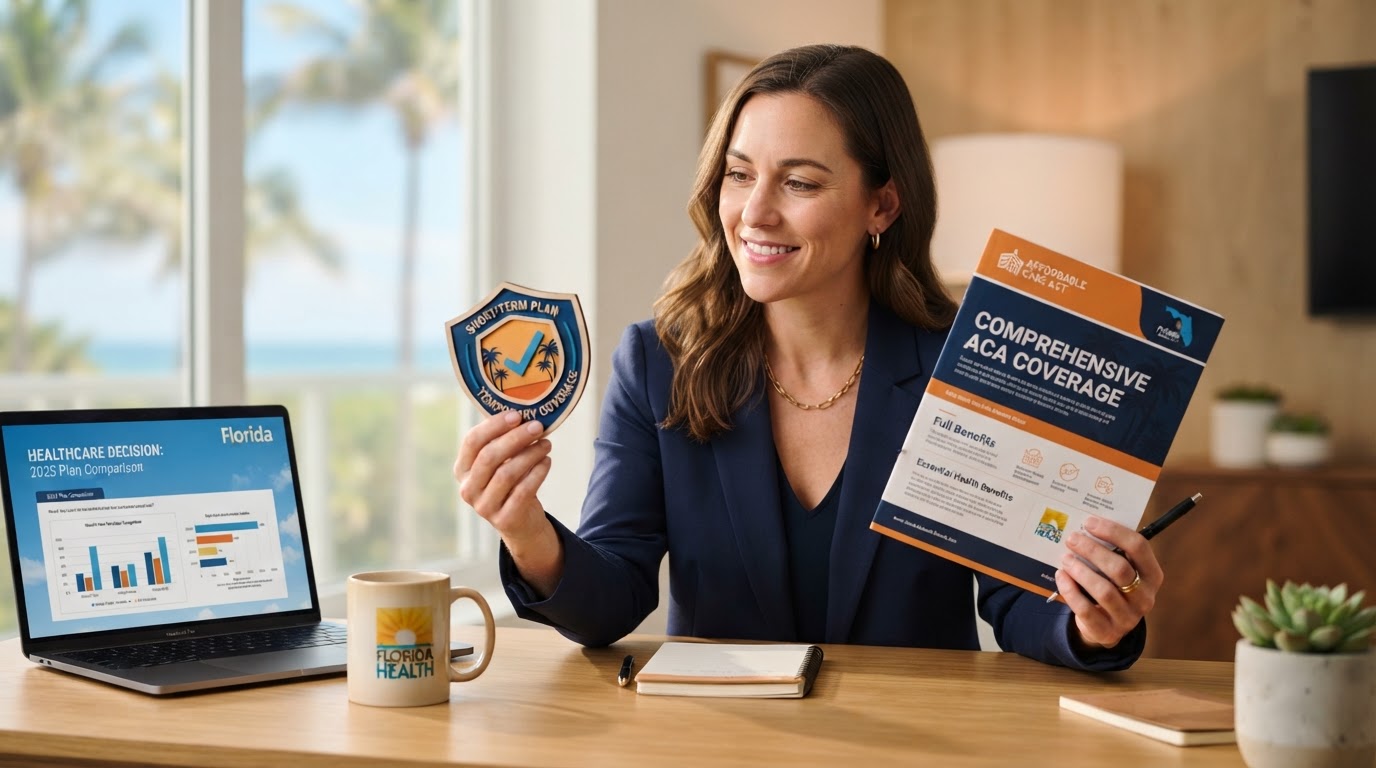
Short Term Health Insurance Florida vs. ACA Plans: What You Need to Know
If you've been searching for short term health insurance Florida options, you're not alone. Thousands of Floridians every year face a gap in coverage — between jobs, waiting for Open Enrollment, or simply looking for a lower monthly premium. Short-term plans can seem like an attractive fix. But before you sign up, it's essential to understand exactly how these plans differ from ACA Marketplace plans — because the differences are significant and can cost you dearly if you're not prepared.
This guide breaks down everything you need to know: what short-term health insurance actually covers in Florida, how it stacks up against ACA plans, and when (if ever) it makes sense to choose one over the other.
What Is Short Term Health Insurance in Florida?
Short-term health insurance is a type of limited-duration coverage designed to bridge temporary gaps. In Florida, these plans are sold by private insurers and are not regulated by the Affordable Care Act (ACA). That distinction matters more than most people realize.
As of federal rules updated in 2024, short-term plans can last up to three months per term, with a maximum of four months including renewals in a 12-month period. Some states allow longer terms, but Florida follows the current federal limitation.
Here's what short-term plans typically offer Florida residents:
- Lower monthly premiums — often 30–60% less than unsubsidized ACA plans
- Fast enrollment — you can often get coverage in 24–48 hours
- Flexible start dates — no waiting for Open Enrollment windows
- Medical underwriting — insurers can deny you based on pre-existing conditions
Because they're not ACA-compliant, short-term plans are not required to cover the 10 essential health benefits mandated by the ACA. That means services like mental health care, prescription drugs, maternity care, and preventive screenings may not be included — or may come with strict sub-limits.
ACA Marketplace Plans in Florida: The Baseline
Florida operates on the federally-facilitated Marketplace (HealthCare.gov), meaning residents shop for ACA plans through the federal platform rather than a state-run exchange. Every ACA plan sold in Florida — whether Bronze, Silver, Gold, or Platinum — must cover all 10 essential health benefits and cannot deny you coverage based on pre-existing conditions.
More importantly, ACA plans come with access to premium tax credits (subsidies) if your household income falls between 100% and 400% of the Federal Poverty Level (FPL) — and thanks to enhanced subsidies under the Inflation Reduction Act (extended through 2025), some Floridians earning above 400% FPL also qualify for help. For a single adult in 2025, 400% FPL is approximately $58,320.
You can explore your potential savings using our ACA subsidy calculator for Florida residents before making any decisions.
ACA plans are available during Open Enrollment (typically November 1 – January 15 in Florida) or during a Special Enrollment Period triggered by a qualifying life event. If you're currently outside Open Enrollment, you may still qualify — learn more in our Special Enrollment Period Florida guide.
Short Term vs. ACA Plans: Side-by-Side Comparison
Here's a quick-reference table to help you see the key differences at a glance:
| Feature | Short-Term Plan | ACA Marketplace Plan |
|---|---|---|
| Pre-existing conditions covered | ❌ Usually excluded | ✅ Always covered |
| Essential health benefits | ❌ Not required | ✅ All 10 required |
| Prescription drug coverage | ❌ Often excluded or limited | ✅ Required |
| Maternity coverage | ❌ Typically not included | ✅ Required |
| Mental health coverage | ❌ Often excluded | ✅ Required |
| Premium tax credits available | ❌ No | ✅ Yes |
| Medical underwriting | ✅ Yes (can be denied) | ❌ No (guaranteed issue) |
| Monthly premium (avg unsubsidized) | Lower ($100–$250/mo) | Higher ($350–$600+/mo) |
| Maximum duration (Florida) | Up to 4 months | 12 months (annual) |
| ACA-compliant | ❌ No | ✅ Yes |
As the table shows, while short-term plans win on price and speed, ACA plans win on protection. For anyone with a health condition — or who might develop one — the coverage gaps in short-term plans can create catastrophic financial exposure.
To better understand which ACA plan tier makes sense for your budget, read our breakdown of ACA metal tiers in Florida.
When Short Term Health Insurance Might Make Sense in Florida
Despite the limitations, there are specific situations where short-term health insurance Florida coverage can serve a legitimate purpose:
- Between jobs: You left an employer plan and your new job's benefits don't start for 60–90 days.
- Waiting for Open Enrollment: You missed Open Enrollment and don't have a qualifying life event for a Special Enrollment Period.
- Young and healthy adults: A 25-year-old with no health conditions who needs something temporary while waiting for an employer plan may find short-term coverage sufficient.
- Recent college graduates: Just aged off a parent's plan and need a bridge while job hunting. (Though check our student health insurance Florida guide first — there may be better options.)
- New Florida residents: Just relocated and need temporary coverage while getting settled. Our new Florida resident health insurance guide covers your full range of options.
Even in these scenarios, always check whether you qualify for a Special Enrollment Period first. Many life events — including moving to Florida, losing job-based coverage, or getting married — trigger a 60-day SEP window to enroll in a full ACA plan.
The Real Risks of Short Term Health Insurance Florida Residents Should Understand
The most dangerous misconception about short-term plans is that they function like real health insurance. They don't — and Florida residents have learned this the hard way.
What can go wrong:
- You develop a condition during your short-term plan (say, high blood pressure or diabetes). When you try to renew or buy a new short-term plan, that condition is now pre-existing and may be excluded or cause denial.
- You need emergency surgery and discover your plan has a $50,000 lifetime benefit cap — far below the actual cost of care.
- You need a prescription medication that isn't covered, or mental health therapy that's excluded entirely.
- Your plan expires after four months and you still don't qualify for Open Enrollment, leaving you without any coverage.
Under the ACA, if you enroll in a Marketplace plan, none of these scenarios apply. Pre-existing conditions must be covered. There are no lifetime or annual dollar limits on essential benefits. And Silver plans with cost-sharing reductions can make out-of-pocket costs genuinely manageable for moderate-income Floridians.
If you're concerned about finding truly affordable health insurance in Florida, there are legitimate ways to lower your ACA premium without sacrificing essential protections.
How Florida's Medicaid Gap Affects Your Options
One factor unique to Florida is the Medicaid coverage gap. Florida has not expanded Medicaid under the ACA, which means adults without dependent children generally must earn at least 100% FPL (about $15,060/year for a single adult in 2025) to qualify for Marketplace subsidies. Those earning below that threshold may fall into a gap where they don't qualify for Medicaid but also don't qualify for ACA subsidies.
If you're in this situation, short-term health insurance may seem like your only affordable option. However, it's worth speaking with a licensed Florida agent to explore every avenue — including Florida KidCare for children, county health department programs, and Federally Qualified Health Centers (FQHCs) — before defaulting to a short-term plan.
How to Choose: A Step-by-Step Decision Framework
Use this process to decide which type of coverage makes sense for you:
- Check your subsidy eligibility — If your income is between 100%–400% FPL (or higher with enhanced subsidies), you likely qualify for a subsidized ACA plan that's more affordable than it looks.
- Check for a Special Enrollment Period — Has anything changed in your life recently? Job loss, relocation, marriage, or birth of a child all trigger SEP eligibility.
- Assess your health needs — Do you take regular prescriptions? Have any ongoing conditions? If yes, an ACA plan is almost certainly the safer choice.
- Calculate the true cost of short-term coverage — Factor in what's not covered. A $150/month short-term plan that excludes prescriptions you pay $300/month for out-of-pocket isn't actually cheaper.
- Consult a licensed Florida agent — A licensed agent at GetCoveredFL.com can run side-by-side comparisons at no cost to you and help you enroll in whatever option fits best.
Related Reading
- ACA Metal Tiers Florida: Bronze, Silver & Gold Guide
- Special Enrollment Period Florida: Your Complete Guide
- Affordable Health Insurance Florida: Lower Your Premium
Get Free Help From a Licensed Florida Agent
Navigating short term health insurance Florida options versus ACA Marketplace plans is genuinely complex — and making the wrong choice can leave you with a five- or six-figure medical bill. The licensed agents at GetCoveredFL.com provide free, unbiased guidance to help Florida residents find the right plan for their situation.
Get free quotes online at GetCoveredFL.com or call (855) 634-5343 to speak directly with a licensed Florida health insurance agent today.
Top-Rated Carriers
- A+ rating
- BBB accredited business
- Customer recommended
Frequently Asked Questions
Is short term health insurance legal in Florida?
Yes, short term health insurance is legal in Florida. These plans are sold by private insurers and regulated at the state level, but they are not ACA-compliant. As of current federal rules, short-term plans can cover up to three months per term, with a maximum of four months including renewals in any 12-month period in Florida.
Can I get a subsidy for short term health insurance in Florida?
No. Premium tax credits (subsidies) are only available for ACA-compliant Marketplace plans purchased through HealthCare.gov. Short-term plans are not eligible for any federal subsidies, which means the sticker price you see is what you pay — making them less of a bargain compared to subsidized ACA plans for income-eligible Floridians.
Does short term health insurance cover pre-existing conditions in Florida?
Generally, no. Short-term health plans in Florida use medical underwriting and can exclude coverage for pre-existing conditions, deny your application outright, or charge higher premiums based on your health history. This is one of the most critical differences from ACA Marketplace plans, which must cover all pre-existing conditions.
What happens when my short term plan expires in Florida?
When your short-term plan expires, you lose coverage. You may be able to renew or purchase a new short-term plan, but any conditions that developed during your prior coverage period may now be excluded as pre-existing. Unless you qualify for a Special Enrollment Period or Open Enrollment has begun, you may face a gap in comprehensive coverage.
When should I choose an ACA plan over short term health insurance in Florida?
Choose an ACA Marketplace plan if you have any pre-existing conditions, take regular prescription medications, need maternity or mental health coverage, or qualify for premium tax credits. An ACA plan provides guaranteed protections and comprehensive benefits that short-term plans simply cannot match. Use a licensed agent at GetCoveredFL.com to compare your real costs side by side.
Ready to find your plan?
Get free quotes from licensed Florida agents in minutes.