How to Estimate Household Income for the ACA Subsidy Calculator in Florida
If you've ever tried to use an ACA subsidy calculator Florida tool and felt confused by the income questions, you're not alone. Thousands of Floridians leave money on the table every year simply because they underestimate or miscalculate their household income — and end up with a smaller premium tax credit than they deserve, or worse, a repayment bill at tax time. Getting this number right is the single most important step in the entire ACA enrollment process. This guide walks you through exactly how to do it.
Why Household Income Estimation Matters for Florida ACA Subsidies
Florida uses the federally-facilitated Marketplace (HealthCare.gov), which means your premium tax credit eligibility is determined entirely by your Modified Adjusted Gross Income (MAGI) relative to the Federal Poverty Level (FPL). For 2026 coverage, the subsidy cliff and eligibility thresholds are based on 2026 FPL figures published by the federal government.
Here's why accuracy is critical:
- Underreporting income can result in a tax repayment (excess advance premium tax credits) when you file your federal return.
- Overreporting income means you receive a smaller subsidy than you're entitled to and overpay premiums all year.
- Florida did not expand Medicaid under the ACA, so if your income falls below 100% FPL, you may fall into the coverage gap and be ineligible for either Medicaid or subsidies. Getting your estimate right can make the difference between qualifying and not.
Subsidies are available for households earning between 100% and 400% FPL — and under the enhanced subsidies still in effect for 2026, households above 400% FPL may also qualify if their benchmark plan premium exceeds a set percentage of income.
Before diving into the math, if you're still deciding between plan types, check out our guide to ACA metal tiers in Florida to understand how Silver plans unlock additional cost-sharing reductions tied to your income.
What Counts as Household Income for ACA Purposes?
The ACA uses Modified Adjusted Gross Income (MAGI), which is slightly different from the number on line 11 of your 1040. Here's what MAGI includes:
Income Sources That Count
- Wages and salaries (W-2 income)
- Self-employment income (net profit after business deductions)
- Freelance and gig economy income (1099-NEC, 1099-K)
- Rental income (net after allowable deductions)
- Alimony received (for divorces finalized before January 1, 2019)
- Social Security benefits — the taxable portion only
- Unemployment compensation (fully countable)
- Investment income — dividends, capital gains, interest
- Retirement distributions from traditional IRAs and 401(k)s (not Roth)
Income Sources That Do NOT Count
- Child support received
- Gifts or inheritances
- Workers' compensation
- Supplemental Security Income (SSI)
- Veterans' disability payments
- Roth IRA distributions (qualified)
MAGI adds back certain deductions to your AGI: student loan interest, IRA deductions, and half of self-employment tax, among others. Most tax software calculates this automatically, but if you're projecting forward, you'll need to estimate.
How to Define Your ACA Household
Your "household" for ACA purposes isn't always the same as who lives under your roof. It's based on who you claim as dependents on your federal tax return.
Household Composition Rules
- Tax filer — always included
- Spouse — included if you file jointly
- Tax dependents — included even if they don't need coverage
- Non-dependent children — counted in their own separate household if they file their own taxes
This matters enormously in Florida, where multigenerational households are common, especially in cities like Miami, Tampa, and Orlando. A college student who files independently is their own household for subsidy purposes — which may help them qualify for student health insurance options through the Marketplace.
Similarly, if you have children who are on your tax return as dependents but are covered under CHIP or Florida KidCare, they still count toward your household size — which lowers your income-to-FPL ratio and can increase your subsidy amount.
Step-by-Step: Estimating Your Annual Income for the ACA Calculator
When you run an ACA subsidy calculator Florida estimate, you'll be asked for projected annual income. Here's how to build that number accurately:
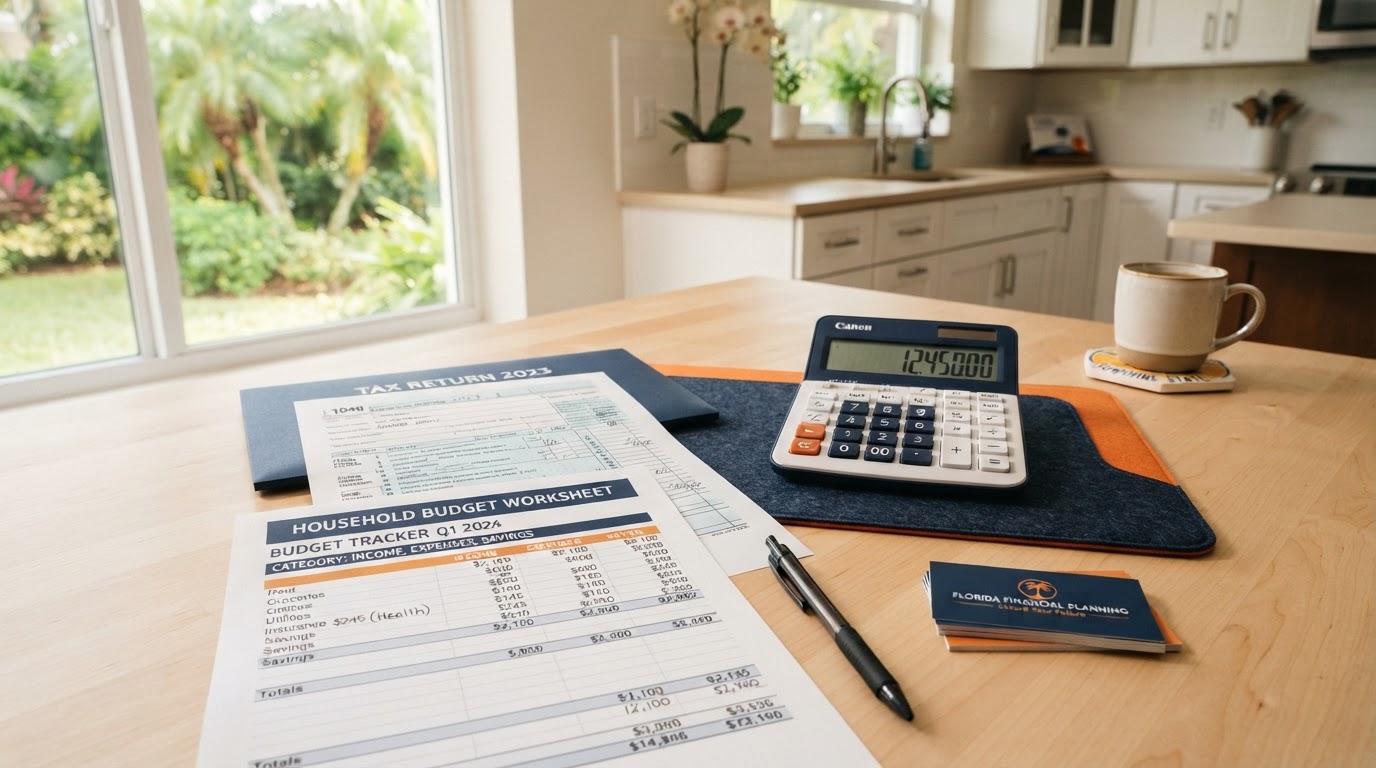
- Start with last year's tax return. Use your MAGI from your most recent 1040 as a baseline.
- Adjust for known changes. Did you get a raise? Start a new job? Retire? Sell a rental property? Add or subtract accordingly.
- Estimate self-employment net income. Project your gross revenue minus expected business expenses. Don't forget to add back half of your self-employment tax.
- Include part-time and seasonal work. Florida has a large seasonal workforce — include all expected earnings, not just your primary job.
- Factor in investment income. If you plan to sell appreciated assets or receive dividends, include those amounts.
- Apply expected above-the-line deductions. HSA contributions, IRA contributions, and student loan interest reduce MAGI. If you plan to maximize HSA contributions in 2026, factor that deduction in — it can meaningfully lower your MAGI and increase your subsidy.
- Cross-check against FPL thresholds. Compare your projected income to the FPL chart below to see where you land.
2026 Federal Poverty Level Reference Table for Florida
Florida follows the continental U.S. FPL guidelines (not Alaska or Hawaii rates).
| Household Size | 100% FPL | 150% FPL | 200% FPL | 250% FPL | 400% FPL |
|---|---|---|---|---|---|
| 1 | ~$15,650 | ~$23,475 | ~$31,300 | ~$39,125 | ~$62,600 |
| 2 | ~$21,150 | ~$31,725 | ~$42,300 | ~$52,875 | ~$84,600 |
| 3 | ~$26,650 | ~$39,975 | ~$53,300 | ~$66,625 | ~$106,600 |
| 4 | ~$32,150 | ~$48,225 | ~$64,300 | ~$80,375 | ~$128,600 |
Note: 2026 FPL figures are approximate and subject to annual adjustment. Confirm exact figures at HealthCare.gov during Open Enrollment.
If your income lands between 150% and 200% FPL, you'll qualify for the most generous cost-sharing reductions on a Silver plan — reducing your deductibles and copays dramatically, not just your premium. This is one of the most underutilized benefits in the Florida Marketplace.
Common Income Estimation Mistakes Florida Residents Make
Even financially savvy Floridians make these errors on their ACA applications:
- Forgetting self-employment income fluctuations. If your income varies month to month, report your best annual estimate and update it on HealthCare.gov if it changes significantly mid-year.
- Ignoring Social Security income. If you're between 60 and 64 and receiving Social Security, the taxable portion counts toward MAGI. Our guide on health insurance before Medicare in Florida covers this scenario in detail.
- Omitting a working spouse's income. Even if your spouse has separate employer coverage, their income is counted in your household MAGI for subsidy purposes.
- Not reporting life changes. A mid-year income increase (new job, freelance contract) that isn't reported can create a large repayment. Report changes within 30 days on HealthCare.gov.
- Confusing gross and net income. For W-2 employees, use gross wages. For self-employed filers, use net profit after business deductions.
If you're gathering documents for your application, our ACA application documents checklist tells you exactly what to have ready.
How the Subsidy Calculation Actually Works
Once you enter your estimated household income and size into the ACA subsidy calculator Florida tool, here's the math behind the scenes:
The government calculates the benchmark premium — the second-lowest-cost Silver plan in your Florida county. Your subsidy equals the difference between that benchmark premium and the maximum you're expected to contribute based on your income percentage.
For example, if the benchmark Silver plan in your county costs $550/month and your maximum expected contribution at your income level is $200/month, your monthly premium tax credit is $350/month, or $4,200/year. You can apply this credit to any metal tier plan.
This is why choosing between Bronze, Silver, and Gold plans matters — the subsidy amount doesn't change based on which plan you choose, but your out-of-pocket costs do. For a deeper comparison, see our guide to comparing health insurance plans in Florida.
If you're enrolling during ACA Open Enrollment for 2026, make sure you have your income estimate ready before the deadline to lock in the best possible subsidy.
Related Reading
- ACA Metal Tiers Florida: Bronze, Silver & Gold Guide
- ACA Application Documents Florida: What You Need
- Affordable Health Insurance Florida: Lower Your Premium
Get Help With Your ACA Subsidy Estimate Today
Estimating household income for the ACA subsidy calculator Florida residents use doesn't have to be stressful. The key is to be thorough, include all income sources, and update HealthCare.gov whenever your situation changes.
At GetCoveredFL.com, our licensed Florida agents help you run accurate subsidy estimates, compare plans side by side, and enroll — all at no cost to you. Call us at (855) 634-5343 or visit GetCoveredFL.com to get your free quote today.
Top-Rated Carriers
- A+ rating
- BBB accredited business
- Customer recommended
Ready to find your plan?
Get free quotes from licensed Florida agents in minutes.